All Categories
Featured

Developing Resilient Supply Chains Via ESG Governance
Table of Contents
Notes: GDP development is defined as the yearly modification in genuine (inflation-adjusted) GDP in the projection year compared to the previous year. Joblessness rate is since December for each year. Core inflation is the year-over-year change in the Customer Prices Index, omitting unpredictable food, energy, alcohol, and tobacco costs, based on the fourth-quarter average for each year.
Yael Selfin, Vice Chair and Chief Economist, KPMG in the UK, was joined by David Smith, Economics Editor at the Sunday Times and Chris Hearld, Group Handling Partner, KPMG, to check out how households and services could be affected and the obstacle for the new government of delivering growth while managing public finances.
The world economy grew by 3.3 percent in 2015, almost identical to the rates taped in 2023 and 2024. The feared drag from greater tariffs did not materialise, showing trade diversion, accommodative financial policy, and carried out tariffs being smaller sized than threatened. Lagged tariff effects may yet emerge. United States growth slowed from 2.8 percent in 2024 to 2.2 percent in 2025, as tariffs, tighter migration policy and raised uncertainty weighed on need.
Top Investment Insights for UK Growth
China and India kept quick growth at 5.0 per cent and 7.4 percent respectively. This reflects postponed tariff impacts and elevated uncertainty dampening financial investment. Development in advanced economies is set to slow to 1.8 per cent in 2026 (United States 2.3 percent, Euro Location 1.3 per cent, Japan 0.8 per cent), with emerging markets growing by 4.0 percent (China 4.6 per cent, India 6.5 per cent). United States CPI inflation (2.7 per cent in December 2025) is anticipated to average 2.6 percent in 2026, showing tariff pass-through and a weaker dollar.
Driving Global Trade Growth for UK
The ECB has actually held its policy rate at 2 per cent and is most likely to keep this position. Long-lasting bond yields remain elevated, with United States 10-year Treasuries around 4.3 percent and Japanese 10-year government bond yields increasing greatly to around 2.3 percent, up from 0.3 per cent in 2023. Tariff results are still working through, while US actions in Venezuela, stress over Greenland, and China's export controls on important minerals raise the threats of further disruption.
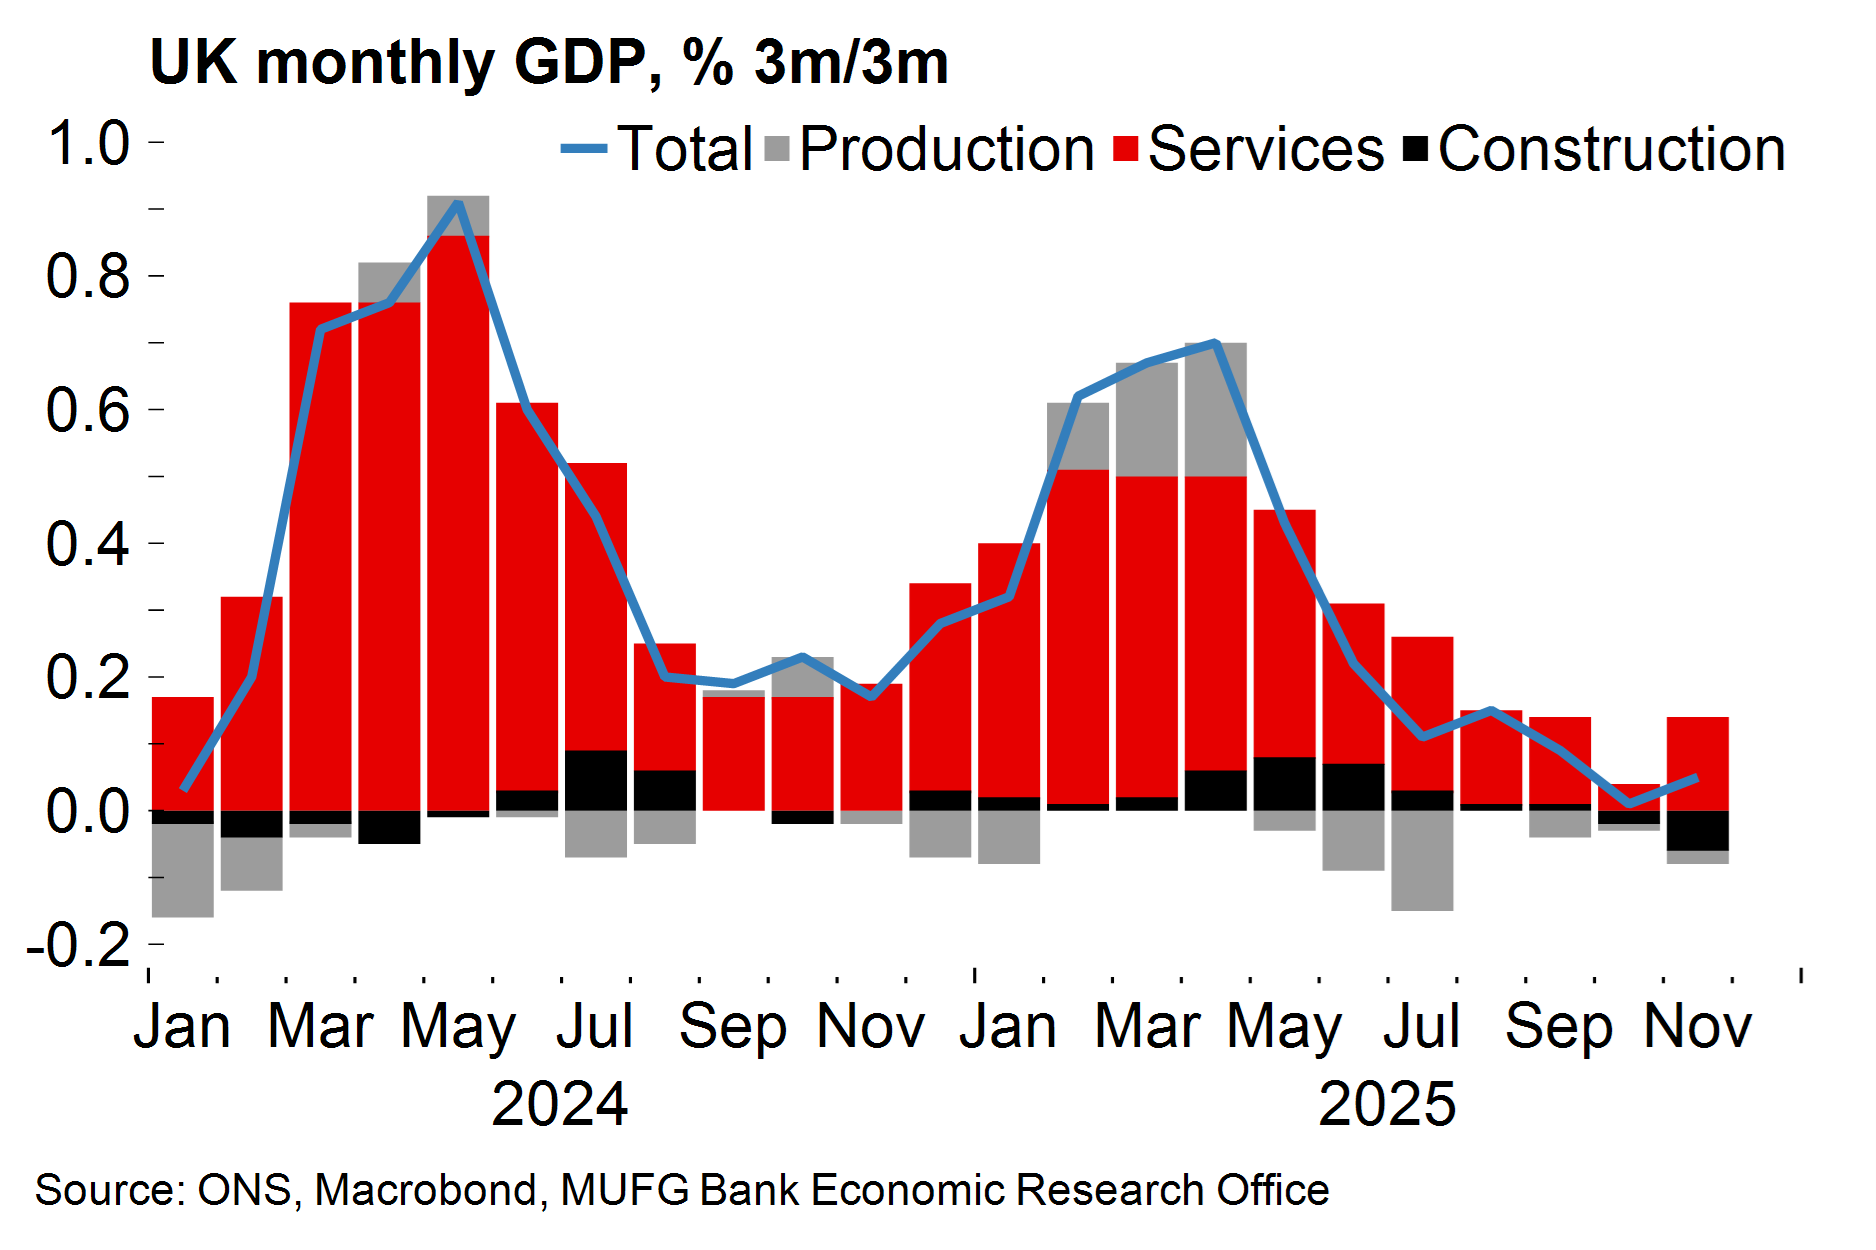
GDP grew by 0.7 per cent in Q1 as companies advanced activity ahead of the April increases in employer National Insurance coverage Contributions and the National Living Wage. Growth then slowed to 0.2 per cent in Q2 and 0.1 percent in Q3, kept back by Budget-related uncertainty and a cyber-attack affecting Jaguar Land Rover.
The near-term outlook is supported by residual fiscal expansion and stable consumption growth. Beyond 2027, development needs to settle somewhat above trend at around 1.3-1.4 per cent. Offered present population forecasts, this implies per capita GDP growth staying listed below 1 per cent from 2027 onwards, underscoring the UK's consistent productivity challenge.
Enhancing Executive Acumen for International UK Growth
Our main forecast is for CPI inflation to average 2.3 per cent in 2026 and to settle around target afterwards. Services inflation (at 4.5 per cent in December) and core inflation (3.2 per cent in December) stay annoyingly elevated, pointing to relentless hidden price pressure.
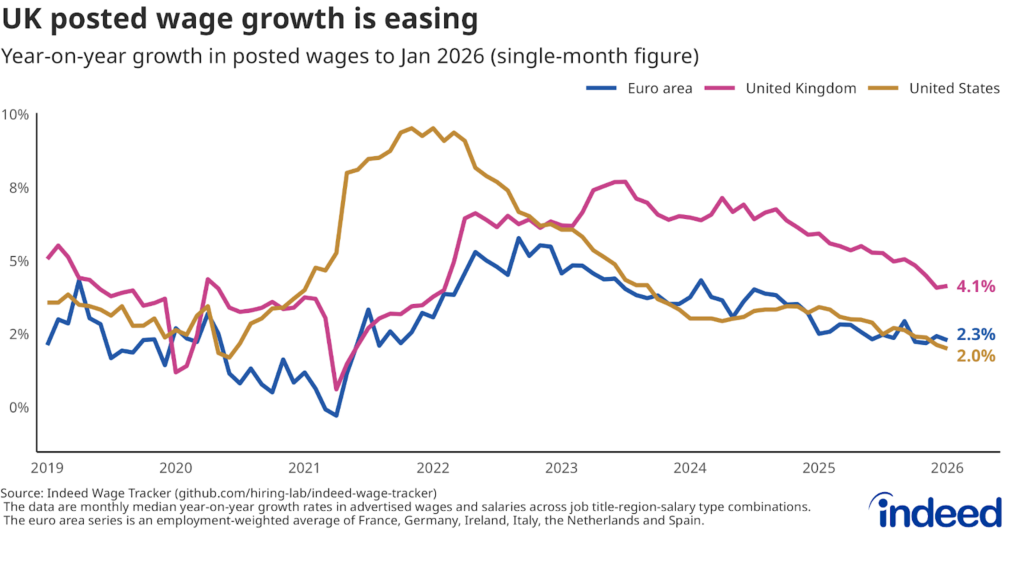
Average incomes growth was 4.7 percent in the three months to November 2025. We project this to slow to around 3.6 percent in 2026 and 3.1 per cent in 2027 as rising joblessness decreases workers' bargaining power a small amounts important for inflation to remain at target on a continual basis.
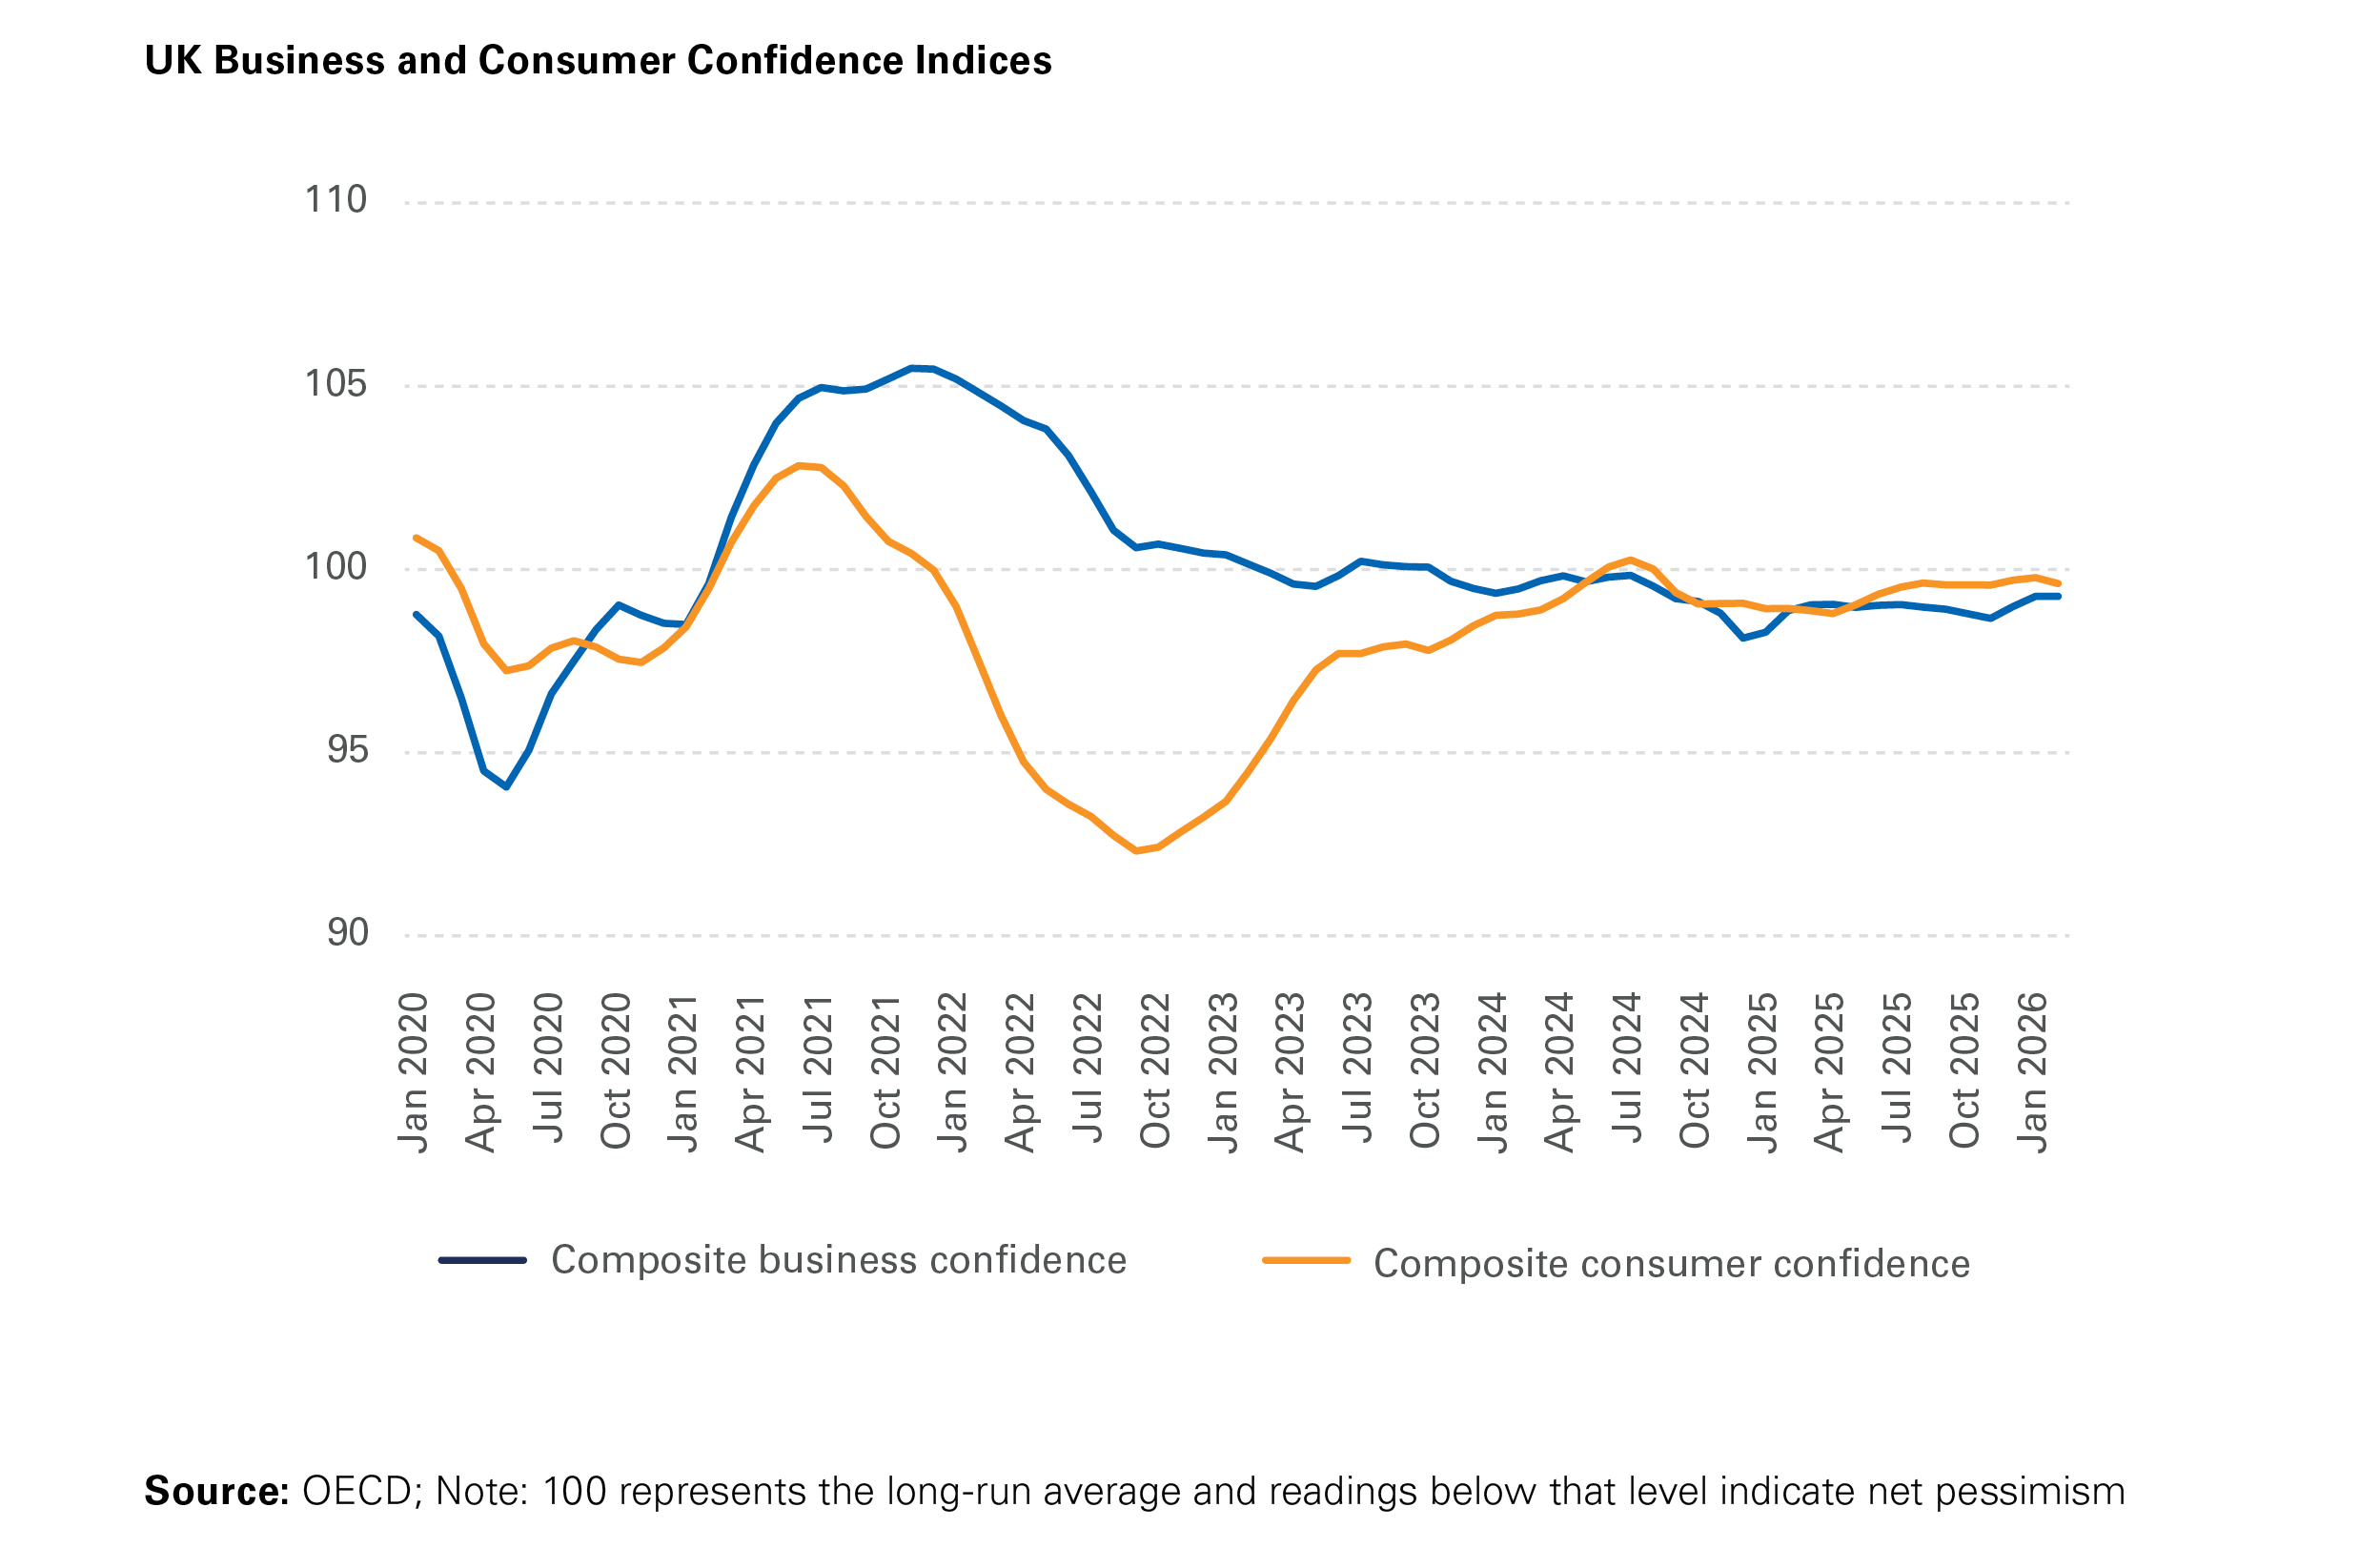
This shows lingering uncertainty about the outlook and the scars from the recent inflation shock. We anticipate this elevated cost savings ratio to continue, constraining usage growth to around 1.0 per cent in 2026 and 1.3 per cent in 2027. With inflation falling and unemployment rising, we anticipate two additional 25 basis point cuts in 2026, bringing the rate to 3.25 per cent by year-endour estimate of the long-run neutral rate.
Investment Banking Developments Impact UK Business Growth
On our projection, the existing budget plan is close to balance by 202930, implying no reliable headroomBox C takes a look at distinctions between the OBR's projection and ours. Public debt continues to increase, with the debt-to-GDP ratio approaching 100 percent by decade-end, limiting the scope for discretionary financial support in future shocks.
By contrast, positive net migration supports fiscal sustainability by broadening the working-age population and broadening the tax base. Increases in company National Insurance coverage Contributions, significant upratings of the National Living Wage (NLW), and reforms to employment rights have actually raised the limited cost of employing by around 7 per cent in real terms for an entry level position.

Latest Posts
Future British Business Trends for 2026
Essential Enterprise Tips for UK Mid-Market Executives
Developing Resilient Supply Chains Via ESG Governance