All Categories
Featured

Essential Enterprise Tips for UK Mid-Market Executives
Table of Contents
"Big ticket purchases were back on the table with vehicle sales notably higher, individuals were already scheduling their summer holidays, and accounting professionals and bookkeepers saw a spike in workload as businesses prepared for the big change of Making Tax Digital which went live at the start of April." Hewson included the recover from last year's cyber-attack on Jaguar Land Rover was continuing to power the production sector as the supply chain raced to take benefit of pent-up need.
"This will have only been exacerbated by the circumstance in the Middle East, which has altered the anticipated path of rates of interest." Barret Kupelian, chief financial expert at PwC, included: "Had the UK economy started to turn a corner after the Autumn Declaration and before the most recent advancements in the Middle East? Today's information recommends it had.
Output grew by 0.5% in the three months to February, with both production and services broadening together. "More notably, this was growth powered by the economic sector rather than the general public sector-dominated parts of the economy that had propped up much of the post-2023 image. That recommended the healing was becoming more comprehensive and more resilient.
Our summer season outlook most likely isn't as bad as England's chances of winning the World Cup this summertime, however it still doesn't produce the most pleasant reading. The Iran dispute has actually risen our inflation forecast, weighing on development and the labour market. Domestic political unpredictability, including yet another change in Prime Minister, adds additional headwinds through higher borrowing costs and gilt yield pressure.
Comparing UK Capital Markets versus Global InvestmentThe threats to that outlook are larger than usual and heavily depending on how the circumstance in the Middle East develops. However the economy has grown at approximately 1.2% through two rough years, and the early signs suggest that resilience will hold. Growth will be slower than last year and with inflation on its way back up the UK is in for another batch of 'stagflation'.
Managing British Corporate Leadership Landscape in 2026
Threats loom big, the war in the Middle East will decide whether the UK economy goes into recession. Partner Between the Iran conflict and yet another tussle for no. 10, this summer's outlook brings a much bigger health caution than typical. Our base case is slower development and rising inflation, however not economic crisis.
The UK is particularly exposed given its dependence on gas for electrical energy prices, which is why the International Monetary Fund (IMF) has revised its UK inflation and growth forecasts more dramatically than any other developed economy. Inflation briefly dipped listed below 3% for the very first time considering that early 2025, however the reprieve will be short-lived.
A weaker labour market and softer demand ought to avoid a repeat of 2022's double-digit spike, limiting second-round results. Our base case is inflation averaging 3.1% in 2026, peaking around 3.5%, before alleviating to 2.5% in 2027, though dangers loom large if the Strait of Hormuz stays closed. The UK labour market was already softening before the current energy shock, with unemployment increasing to 5.0% and vacancies at their least expensive considering that the pandemic.
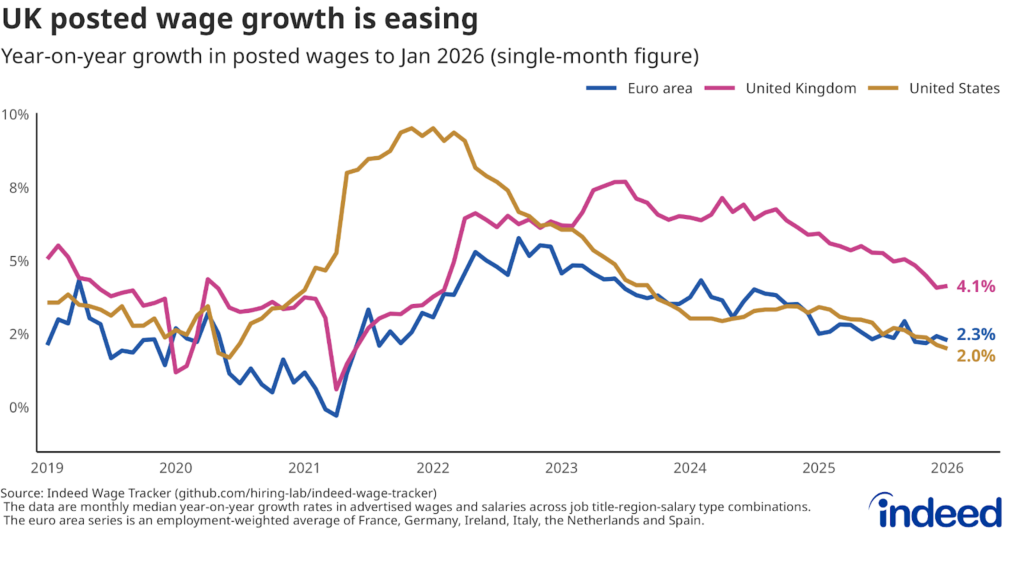
Why Digital Tools Matter for British Mid-MarketFirms are not yet shedding personnel, but unwillingness to employ is broadening the gap in between job development and population development. Higher energy expenses will intensify the pressure, and we expect unemployment to peak at 5.3% by year end. With wage growth slowing to around 3.75% and inflation heading towards 3.5%, real pay looks set to be stagnant another difficult year for living standards.
3 elements restrict the case for walkings: the energy shock is smaller than in 2022, rates are already at a restrictive level, and a weaker economy lowers the threat of second-round inflation results. That stated, rate rises can not be dismissed if energy prices rise further. Gilt yields are most likely to stay elevated regardless, driven by the UK's inflation sensitivity and political uncertainty around a possible change of Prime Minister, keeping borrowing costs high throughout the economy even if the policy rate remain on hold.
How Digital Innovation Optimises Workflows for 2026
The UK is especially exposed given its reliance on gas for electrical energy pricing, which is why the International Monetary Fund (IMF) has actually modified its UK inflation and development projections more dramatically than any other developed economy. Inflation briefly dipped below 3% for the very first time considering that early 2025, however the reprieve will be short-term.
A weaker labour market and softer need should prevent a repeat of 2022's double-digit spike, limiting second-round impacts. Our base case is inflation averaging 3.1% in 2026, peaking around 3.5%, before relieving to 2.5% in 2027, though threats loom big if the Strait of Hormuz remains closed. The UK labour market was already softening before the newest energy shock, with joblessness increasing to 5.0% and jobs at their most affordable considering that the pandemic.
Firms are not yet shedding personnel, however unwillingness to employ is broadening the space in between task development and population growth. Higher energy costs will compound the pressure, and we anticipate unemployment to peak at 5.3% by year end. With wage development slowing to around 3.75% and inflation heading towards 3.5%, real pay looks set to be stagnant another challenging year for living requirements.
Three aspects restrict the case for hikes: the energy shock is smaller than in 2022, rates are currently at a limiting level, and a weaker economy decreases the danger of second-round inflation effects. That stated, rate increases can not be ruled out if energy costs surge even more. Gilt yields are likely to remain raised regardless, driven by the UK's inflation level of sensitivity and political unpredictability around a potential modification of Prime Minister, keeping borrowing costs high across the economy even if the policy rate remain on hold.

Latest Posts
Future British Business Trends for 2026
Essential Enterprise Tips for UK Mid-Market Executives
Developing Resilient Supply Chains Via ESG Governance