All Categories
Featured


Driving Sustainable Value Through ESG Supply Chains
Table of Contents
In particular, tax and legal direct exposure can begin surprisingly early, even if overseas revenue still feels "small". abroad activity can set off domestic taxation in another jurisdiction faster than many owner-managers expect. cross-border sales, digital services and varying registration limits can create compliance commitments and pricing concerns. specifically pertinent where IP, management charges, or intercompany/group deals are involved.
Analyzing ESG Finance for 2026 UK Firmsmaking sure IP, brand name, trade assets and other intangibles are held and safeguarded in structures that minimize exposure as global activity grows. utilizing the ideal entities for the right risks, so operational direct exposure in one location doesn't needlessly endanger properties held somewhere else. This is where an efficient contemporary Financing Director includes genuine strategic value.
They understand what to search for, when "small" overseas activity starts to produce big implications, and how to avoid sleepwalking into preventable exposure. In practice, a strong FD will emerge the concerns early, commission the ideal professional guidance, and coordinate the moving parts across tax advisers, legal counsel and internal stakeholders.
Together with the macro picture, AI is becoming a specifying force in how finance works operate. Worldwide, adoption amongst SMEs is rising quickly, and those who move initially tend to get an edge in efficiency, decision speed and funding. Tools that analyse spend, flag anomalies, enhance forecasting and create commentary are moving from speculative to mainstream.
A disciplined, FD-led financing function does the opposite: it develops a solid structure for automation to provide reliable insight. Picking appropriate automation tools for the size and intricacy of the service.
Driving Sustainable Returns Through Ethical Supply Chains
In 2026, SMEs will contend on financial clearness as much as item or service quality. AI expands the gap in between disciplined and undisciplined companies.
Fixed headcount becomes a larger dedication, particularly in junior or operational functions where performance can be variable. Hiring mistakes become more pricey, not only financially but in management time. Minimizing permanent hiring and being more selective about in-house roles. Relying more heavily on fractional professionals, including fractional FD services. Increasing automation and AI adoption to simplify documentation-heavy or repeated workflows.

They model labor force circumstances, hire vs contract out vs automate, and show how these choices affect cashflow, margin and functional threat. Offered this backdrop, what should an SME's finance management, whether internal or outsourced, focus on over the next 18 months? rolling projections, situation planning, debtor management and provider negotiations that go beyond spreadsheets into structured process, supported by strong cashflow management.
Analyzing ESG Finance for 2026 UK Firmsturning reporting into lender- and investor-ready packs through strategic financing support. keeping an eye on FX, landed cost and regional success with continuous scenario modelling. supported with clean information and automated control panels produced via strong management reporting. These are not administrative tasks, they are tactical enablers. And for many SMEs, the most cost-effective path to this capability is an outsourced Finance Director who brings senior-level clearness without including work risk.
Essential Methods to Scale Mid-Market Global Growth
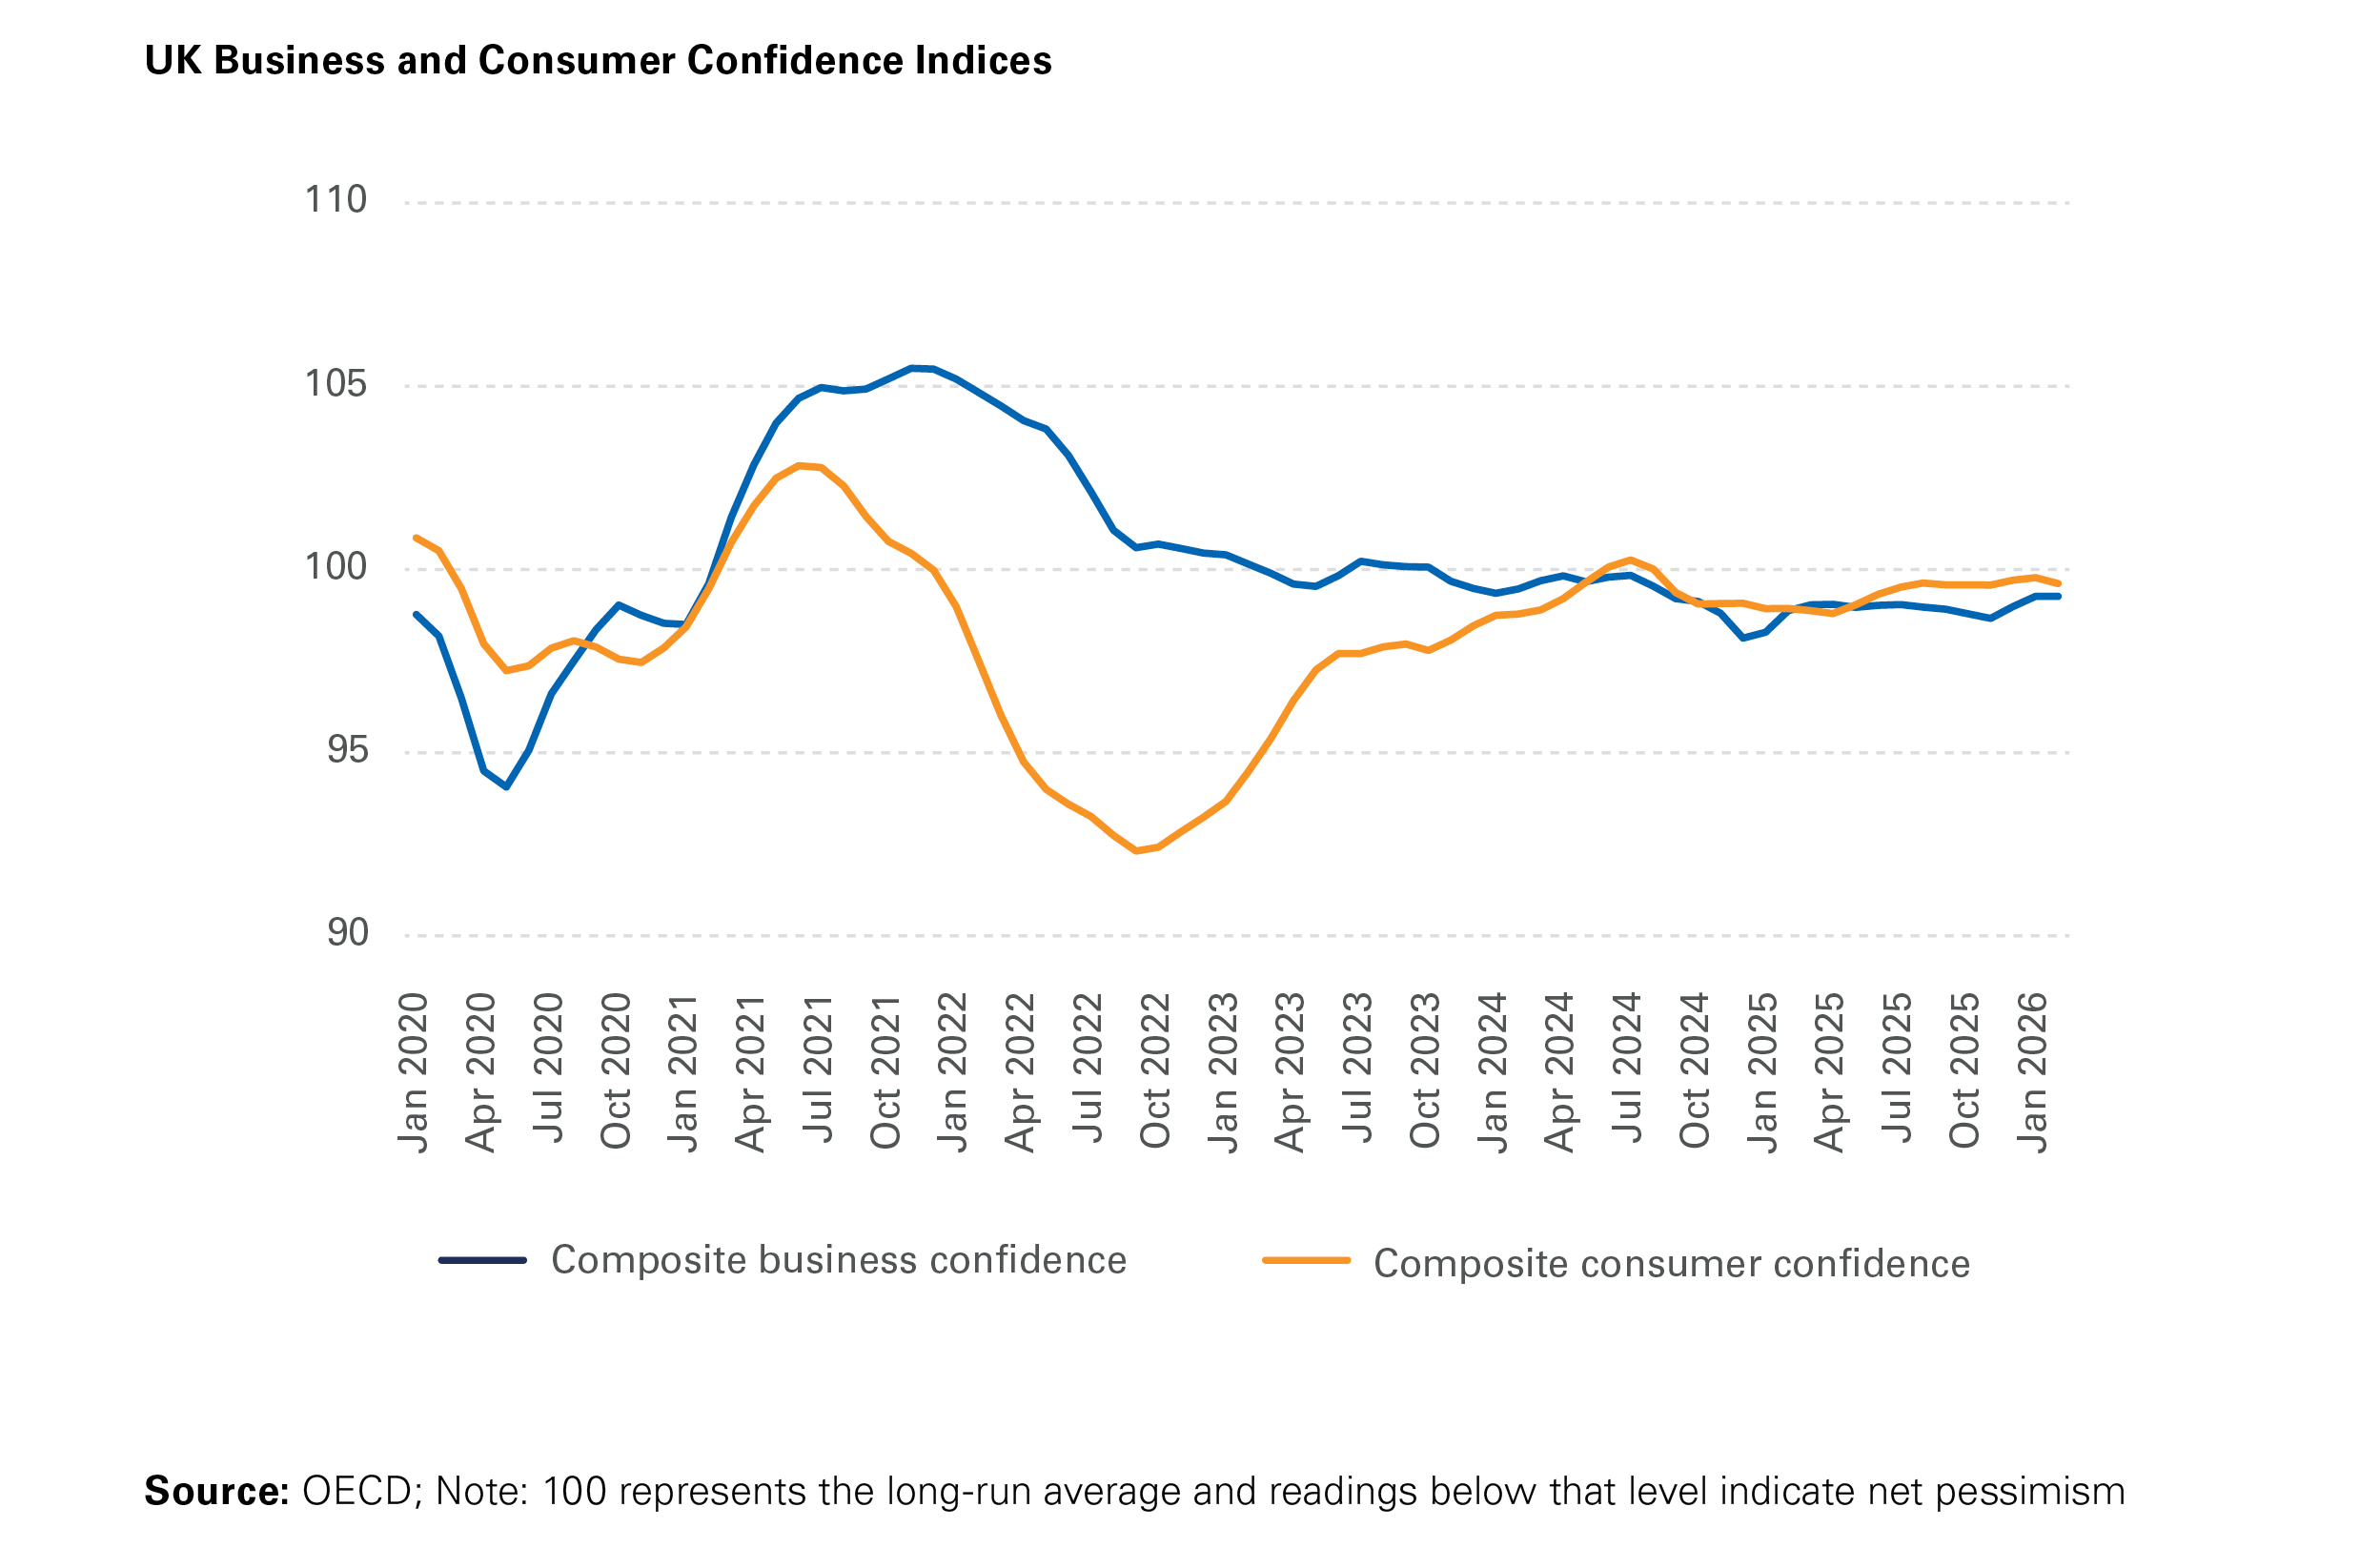
For businesses considering their next relocation, the availability and cost of financing matters as much as self-confidence. What we are seeing now is a market where, in spite of mixed sentiment, the conditions for investment are enhancing in useful and quantifiable methods. It would be fair to say that self-confidence amongst SMEs has softened over the past year.
What has altered is presence. Businesses now have a clearer view of their cost base, their tax position and the broader financial background. That clearness, even if it includes tough decisions, allows companies to plan. Progressively, we are hearing companies explain 2026 as a year of shipment instead of hold-up.
Companies understand that capital is offered at a reasonable cost, which this produces a chance to advance growth strategies that might have been parked while conditions were less particular. While confidence might be weaker than it was 12 or 18 months ago, the tone of conversations has become more constructive.
Over the last few years, possession financing brought in particular attention, helped by tax incentives that made it especially attractive. A few of those advantages have actually since minimized, however instead of dampening activity, we are seeing need across the complete series of commercial loaning. Property-backed finance, structured financing and asset financing are all in play.
The loan provider side of the market is also shifting in favour of debtors. There is an abundance of capital readily available, providing requirements are softening, and prices is relieving.
Optimizing Corporate Team Performance Through AI
Businesses that restrict themselves to a single lender are undoubtedly limiting their choices. A whole-of-market technique allows funding to be structured around the requirements of business instead of the restraints of a particular product. Dealing with knowledgeable commercial financing brokers provides companies access to a large lending universe and a much broader variety of services.
It likewise means businesses can respond quicker as conditions develop, instead of being connected to one route. Looking ahead, I think the next stage will favour companies that want to make thought about financial investment decisions. After a suppressed second half of 2025, the combination of capital accessibility, loan provider cravings and improving rates produces a platform for development.
Those who continue to postpone decisions might discover themselves stalling while the marketplace carries on. In a more competitive environment, that carries its own risks. Turnover and profitability are not ensured simply by waiting on conditions to become perfect. The message I would offer to company owner is not to neglect risk, but to identify chance.
For firms with ambition, a clear strategy and the willingness to engage effectively with the funding landscape, this is a duration that can be utilized to support sustainable development rather than just to tread water.
This post has actually been gotten ready for information functions only, does not make up an analysis of all potentially material problems and undergoes alter at any time without previous notification. NatWest Markets does not undertake to update you of such modifications. It is indicative only and is not binding. Besides as suggested, this article has actually been prepared on the basis of openly available info thought to be reputable but no representation, service warranty, endeavor or guarantee of any kind, reveal or indicated, is made as to the adequacy, accuracy, efficiency or reasonableness of the info included in this short article, nor does NatWest Markets accept any commitment to any recipient to upgrade or fix any information included herein.
Smart Leadership to Guide 2026 Mid-Market Growth
The views expressed herein may not be unbiased or independent of the interests of the authors or other NatWest Markets trading desks, who might be active individuals in the markets, financial investments or strategies described in this post. NatWest Markets will not act and has actually not acted as your legal, tax, regulatory, accounting or financial investment adviser; nor does NatWest Markets owe any fiduciary tasks to you in connection with this, and/or any related transaction and no reliance might be positioned on NatWest Markets for investment suggestions or recommendations of any sort.

Latest Posts
Future British Business Trends for 2026
Essential Enterprise Tips for UK Mid-Market Executives
Developing Resilient Supply Chains Via ESG Governance