All Categories
Featured

Strategic Business Funding Projections for UK Growth Sectors
Table of Contents
Notes: GDP development is defined as the annual modification in real (inflation-adjusted) GDP in the forecast year compared with the previous year. Joblessness rate is as of December for each year. Core inflation is the year-over-year modification in the Customer Rates Index, excluding unstable food, energy, alcohol, and tobacco rates, based on the fourth-quarter average for each year.
Yael Selfin, Vice Chair and Chief Financial Expert, KPMG in the UK, was signed up with by David Smith, Economics Editor at the Sunday Times and Chris Hearld, Group Managing Partner, KPMG, to explore how households and businesses might be affected and the obstacle for the brand-new federal government of delivering development while managing public financial resources.
The world economy grew by 3.3 per cent last year, practically identical to the rates taped in 2023 and 2024. The feared drag from greater tariffs did not materialise, showing trade diversion, accommodative financial policy, and implemented tariffs being smaller sized than threatened. Lagged tariff results may yet emerge. United States development slowed from 2.8 percent in 2024 to 2.2 per cent in 2025, as tariffs, tighter immigration policy and raised uncertainty weighed on need.
Analysing the British Economic Dynamics Within Global Frontiers
China and India preserved quick expansion at 5.0 per cent and 7.4 per cent respectively. This reflects delayed tariff results and raised unpredictability dampening investment. Growth in innovative economies is set to slow to 1.8 per cent in 2026 (United States 2.3 percent, Euro Area 1.3 percent, Japan 0.8 per cent), with emerging markets growing by 4.0 per cent (China 4.6 per cent, India 6.5 per cent). United States CPI inflation (2.7 percent in December 2025) is anticipated to average 2.6 percent in 2026, reflecting tariff pass-through and a weaker dollar.
Developing Sustainable Value Networks Via Strategic Governance
The ECB has held its policy rate at 2 percent and is likely to keep this stance. Long-term bond yields stay raised, with United States 10-year Treasuries around 4.3 per cent and Japanese 10-year government bond yields rising greatly to around 2.3 per cent, up from 0.3 per cent in 2023. Tariff effects are still resolving, while United States actions in Venezuela, stress over Greenland, and China's export controls on critical minerals raise the risks of more disturbance.
GDP grew by 0.7 per cent in Q1 as companies advanced activity ahead of the April increases in employer National Insurance Contributions and the National Living Wage. Development then slowed to 0.2 per cent in Q2 and 0.1 percent in Q3, held back by Budget-related unpredictability and a cyber-attack affecting Jaguar Land Rover.
The near-term outlook is supported by residual financial expansion and stable usage development. Beyond 2027, growth ought to settle a little above pattern at around 1.3-1.4 percent. Given existing population projections, this indicates per capita GDP development staying below 1 per cent from 2027 onwards, underscoring the UK's relentless efficiency difficulty.
Analysing British Venture Investment Trends for 2026
Our central forecast is for CPI inflation to average 2.3 per cent in 2026 and to settle around target thereafter. Nevertheless, services inflation (at 4.5 per cent in December) and core inflation (3.2 per cent in December) remain uncomfortably raised, pointing to persistent underlying cost pressure. As analyzed in Box E of this Outlook, this shows mostly a sharp rise in labour supply as participation increased, rather than extensive job losses.
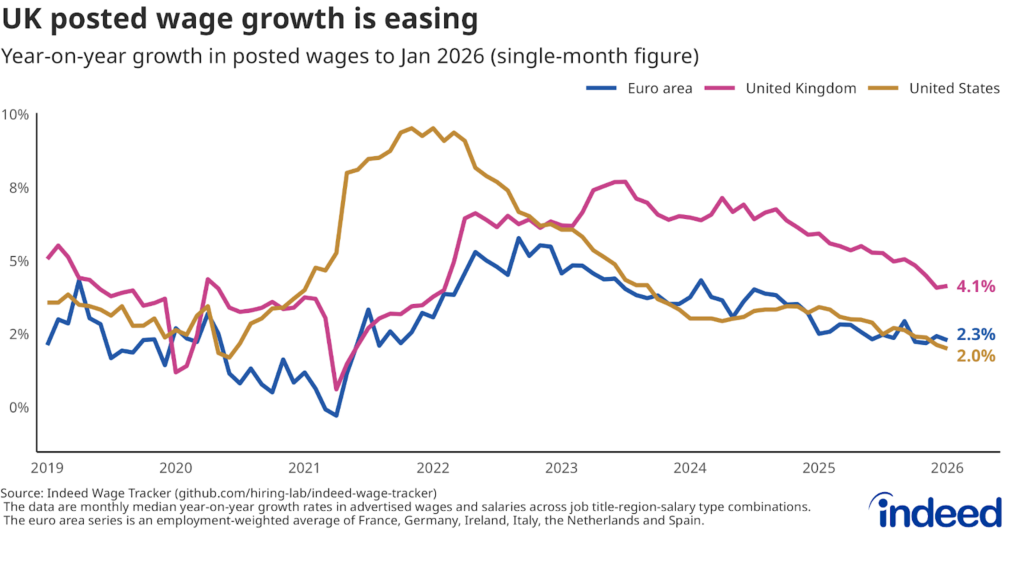
Typical profits growth was 4.7 percent in the three months to November 2025. We project this to slow to around 3.6 percent in 2026 and 3.1 percent in 2027 as increasing unemployment minimizes workers' bargaining power a moderation necessary for inflation to remain at target on a continual basis.
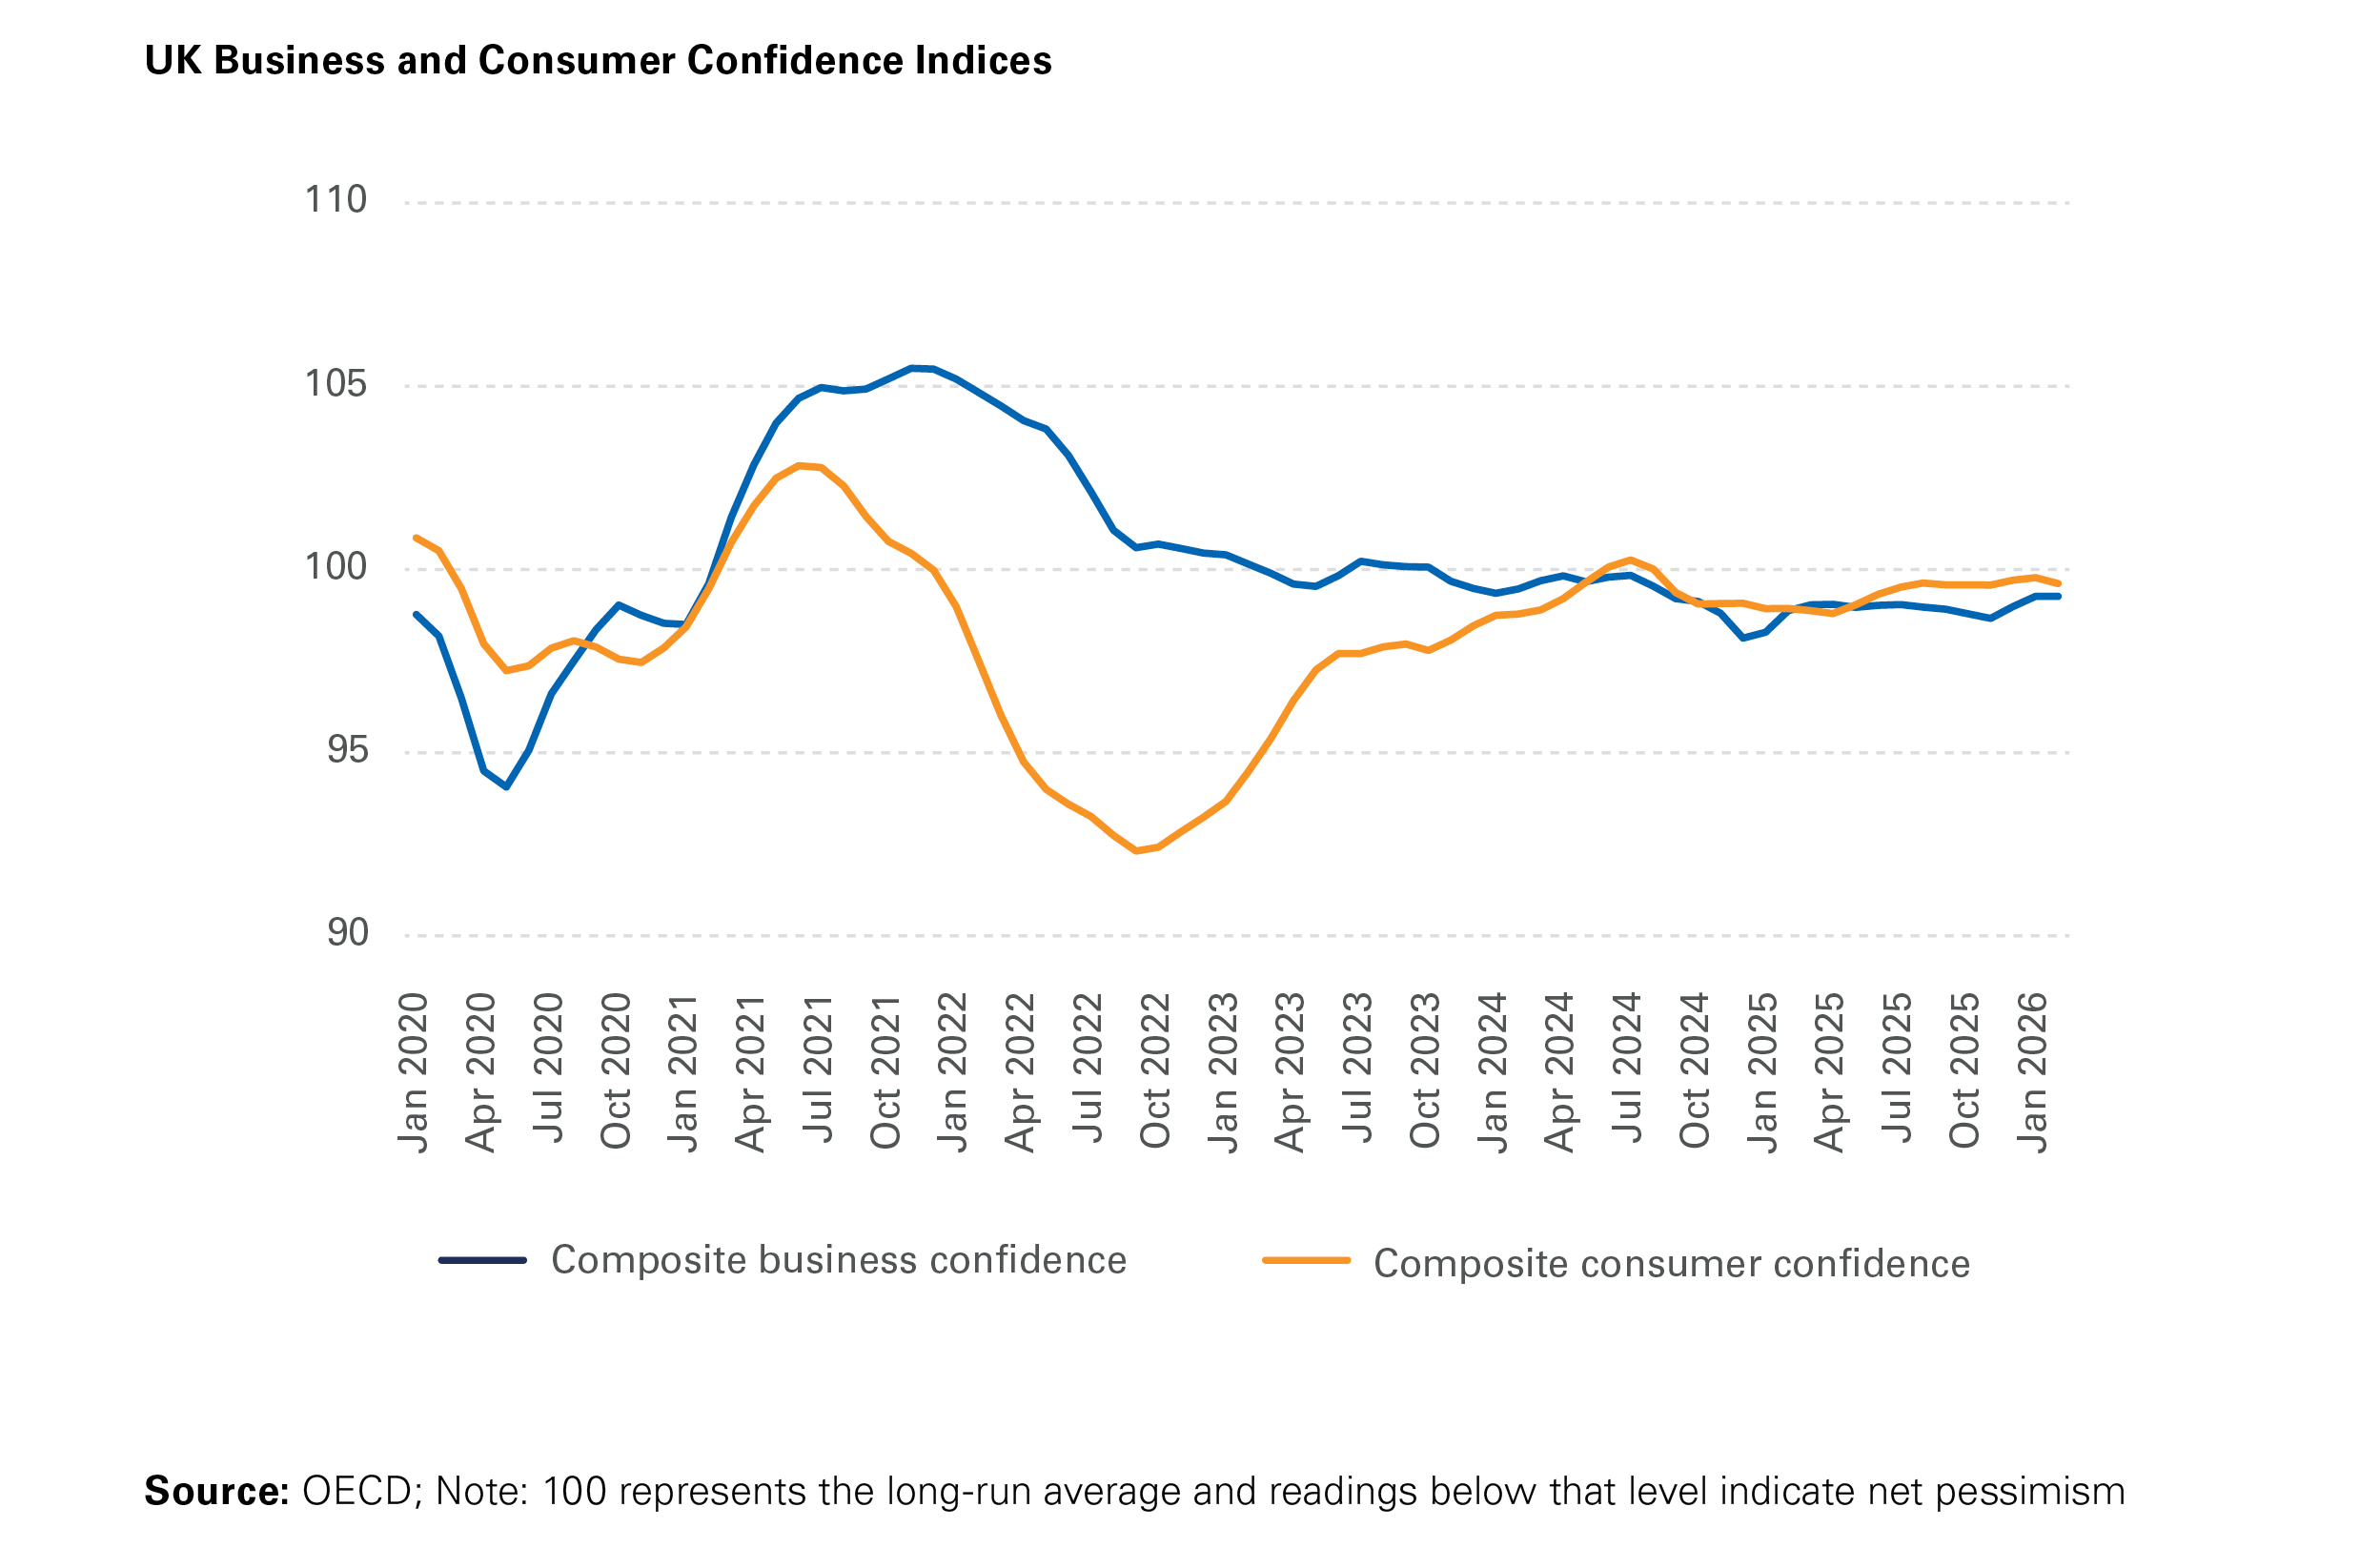
This shows sticking around unpredictability about the outlook and the scars from the recent inflation shock. We expect this elevated cost savings ratio to continue, constraining consumption development to around 1.0 percent in 2026 and 1.3 percent in 2027. With inflation falling and unemployment rising, we anticipate 2 further 25 basis point cuts in 2026, bringing the rate to 3.25 percent by year-endour price quote of the long-run neutral rate.
Navigating Business Funding Trends Within the UK
On our projection, the present budget is close to balance by 202930, suggesting no efficient headroomBox C analyzes distinctions between the OBR's projection and ours. Public financial obligation continues to increase, with the debt-to-GDP ratio approaching 100 per cent by decade-end, restricting the scope for discretionary fiscal assistance in future shocks.
Analyzing International Trade Outlooks for British IndustryBy contrast, positive net migration supports financial sustainability by expanding the working-age population and widening the tax base. Boosts in company National Insurance Contributions, significant upratings of the National Living Wage (NLW), and reforms to work rights have raised the marginal expense of hiring by around 7 per cent in real terms for an entry level position.

Latest Posts
Future British Business Trends for 2026
Essential Enterprise Tips for UK Mid-Market Executives
Developing Resilient Supply Chains Via ESG Governance